


Big Week Ahead For Economic Data & Elections

Perhaps in part to get off the train of talking about nothing but AI, let’s look at the week ahead. It’s a fairly busy week, again, with elections and big data. We entered the week with some of the usual Black Monday calls after October ended on a very sour note. Unsurprisingly, that didn’t happen, but we faded initial green, with AI taking it on the chin, again. What lies ahead?
Tuesday will bring AMD, which will get a lot of attention after last week’s Intel (INTC) miss. Wednesday brings UBER, ARM, and Qualcomm (QCOM) for more looks at tech.
I’m broadly constructive on these reports, though I’ve also been unusually stone-cold in my expectations accuracy, of late. Given how most stocks have been de-risked, the bar shouldn’t be all that high. That said, fear remains high, particularly in AI, so investors probably won’t treat misses kindly. If tech earnings aren’t viewed positively, expect crash chatter to rise. My main fear remains credit stress, as it’s been quite slow to fade.
From an economic data standpoint, we had ISM Manufacturing today. That was quite good, with everything showing growth. Even better, we saw the Prices Paid subindex go down a bit, though it’s still quite high. Wednesday is the ISM Services report. That’s also held up quite well, and the expectation is we see more of the same.
The big, important report is the Nonfarm Payrolls report on Friday. Any big swings in the report can really move markets. That said, expectations are pretty moderate, with 55K expected versus the previous 29K, and the unemployment rate is expected to hold steady at 4.2%. In general, expectations are that we’ve been in a low-hire, low-fire environment for a while, where we are stabilizing or maybe even rebounding. Goldilocks is ideal, with reasonably steady employment growth without much wage inflation.
The other big news for the week, of course, are midterm elections in the US. The expectation is that it’s a real possibility Democrats assume leadership in the House and Senate, with the House more likely. Either way, the Republicans would lose their full control of the Federal government, which strikes me as the important part. The big surprise would be if Republicans keep all branches, but that seems unlikely.
If nothing else, all that brings a lot of potential for volatility, something markets are already well aware of. For instance, the put/call ratio, pictured above, continues to climb, indicating puts are being bought over calls, as investors buy insurance on stocks, or bet on further declines. That’s where we are. The question is where do we go?
Of course, I don’t know. I will say that despite the buildup of puts, we’re also seeing bullish trades today, as well. Rhodie House Options Intel is highlighting big money buying risk reversals in SPY, expecting a bounce soon. There are also heavy QQQ call buys, expecting upside there. It’s worth noting those calls are longer-term in nature, generally targeting 2-9 months. Bulls are dominating recent positioning, but they’re patient bulls. Given what we know right now, that makes sense to me.
ISM Manufacturing PMI was 55 vs. exp. 54.6. Interestingly, Prices Paid fell a bit, though it’s still at 75.2.
Oil was -7% yesterday as talk of negotiations advanced, though it’s bouncing back a bit today.
Equity put/call ratio hit the highest of the year, implying the stock market is very defensive.
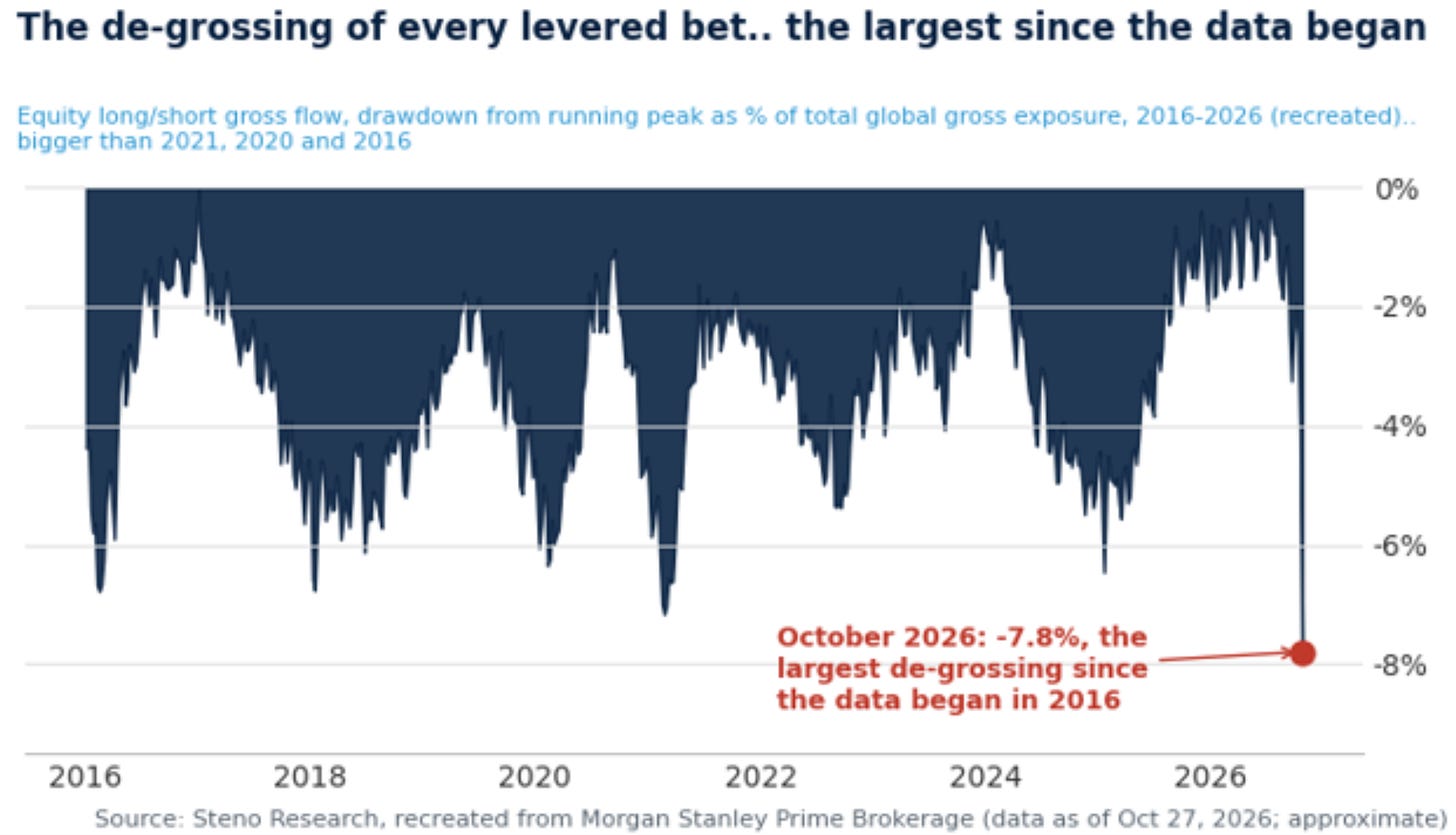
AI got kicked in the teeth again yesterday, as investors continue to run for the exits. It’s getting a bit of a bid again today, though, with semiconductors (SMH) leading the charge, up almost 2%. Can it stay green, with liquidity continuing to show stress?
Anthropic said their revenue is $17B, up 1,127% from a year ago. It should also be encouraging that their compute bill is growing slower than revenue but fear reigns, lately.
Aehr Test Systems (AEHR) is up 14% after beating earnings, upping guidance, and having strong bookings.
Palantir (PLTR) had stellar earnings and guidance but is down -7%. Let’s say it’s because commercial bookings slowed.
AAPL had great earnings, though China business was weak. Inventory also rose. The guide was for slower growth and lower margins, which is probably why the stock is -4%.
JOLTS Job Openings, ADP Employment, and Factory Orders today, plus Federal elections tonight.
Bottom Line: AI was kicked hard again yesterday as liquidity hasn’t come back.
Click here to schedule a meeting — I’m here to help you take the next step toward financial freedom.
Disclosures/Regulation:
This content is intended to provide general information about Lloyd Financial. It is not intended to offer or deliver investment advice in any way. Information regarding investment services are provided solely to gain an understanding of our investment philosophy, our strategies and to be able to contact us for further information.
All information has been obtained from sources believed to be reliable, but its accuracy is not guaranteed. There is no representation or warranty as to the current accuracy, reliability or completeness of, nor liability for, decisions based on such information and it should not be relied on as such.
The views expressed in this commentary are subject to change based on market and other conditions. These documents may contain certain statements that may be deemed forward‐looking statements. Please note that any such statements are not guarantees of any future performance and actual results or developments may differ materially from those projected. Any projections, market outlooks, or estimates are based upon certain assumptions and should not be construed as indicative of actual events that will occur.
Want a clearer view of where you stand? Schedule a free portfolio analysis.
Comments