Article
Qualified Charitable Distributions (QCDs): A Tax-Efficient Way to Give and Reduce Income
Qualified Charitable Distributions (QCDs): A Tax-Efficient Way to Give and Reduce Income
For retirees who are charitably inclined, Qualified Charitable Distributions (QCDs) are one of the most underutilized—and powerful—tools in financial planning. Done correctly, they can reduce taxable income, satisfy Required Minimum Distributions (RMDs), and support causes you care about—all in one move.
Let’s break down how they work and why they should be part of your retirement strategy.
What Is a QCD?
A Qualified Charitable Distribution allows individuals age 70½ or older to transfer money directly from an IRA to a qualified charity.
The key benefit: That distribution is excluded from your taxable income.
This is different from taking a normal IRA distribution and then writing a check to a charity, which would still count as taxable income (even if you itemize deductions).
Key Rules to Know
Age Requirement: You must be at least 70½ at the time of the distribution
Eligible Accounts: Traditional IRAs (not 401(k)s unless rolled into an IRA)
Annual Limit: Up to $100,000 per person per year (indexed for inflation starting in 2024)
Direct Transfer: Funds must go directly from the IRA custodian to the charity
Qualified Charity: Must be a 501(c)(3) organization (donor-advised funds and private foundations don’t qualify)
QCDs and Required Minimum Distributions (RMDs)
Once you reach RMD age (currently 73 for most retirees), QCDs become even more valuable.
A QCD:
Counts toward your RMD
But does NOT increase your taxable income
This is a huge advantage.
Example:
RMD = $40,000
You donate $20,000 via QCD
Result:
Only $20,000 is taxable income
The other $20,000 is completely excluded
That’s far more efficient than taking the full RMD and donating after the fact.
Why QCDs Matter in Financial Planning
1. Lower Your Taxable Income
Reducing Adjusted Gross Income (AGI) has a ripple effect:
Lower Medicare premiums (IRMAA brackets)
Reduced taxation of Social Security
Potentially fewer phaseouts of deductions/credits
2. Better Than Charitable Deductions (for Many Clients)
With today’s higher standard deduction, many retirees don’t itemize. That means:
Traditional charitable giving provides no tax benefit
QCDs solve this:
You get a tax benefit whether you itemize or not
3. Strategic Tax Bracket Management
QCDs can help:
Keep clients in lower tax brackets
Avoid triggering higher capital gains rates
Reduce overall lifetime tax liability
This is especially important in years where income management matters—like Roth conversion planning.
4. Ideal for “Charitably Inclined but Tax-Inefficient” Clients
Many retirees say:
“I give every year anyway.”
QCDs simply make that giving more efficient.
Advanced Planning Strategies
Pair QCDs with Roth Conversions
Use QCDs to offset RMD income
Then execute Roth conversions in lower tax brackets
Bunching Strategy Alternative
Instead of bunching deductions:
Use QCDs annually to smooth income and taxes
Married Couples Advantage
Each spouse can do up to $100,000 from their own IRA
Potentially $200,000/year in tax-free charitable giving
Common Mistakes to Avoid
Taking the distribution personally first (must go direct)
Trying to use QCDs from a 401(k)
Donating to non-qualified organizations
Missing proper documentation from the charity
Who Should Consider QCDs?
QCDs are especially powerful for:
Retirees with large IRA balances
Individuals subject to RMDs
Clients who take the standard deduction
Those concerned about Medicare premium surcharges
Anyone consistently giving to charity
Qualified Charitable Distributions are one of the cleanest ways to:
Reduce taxes
Control income
Support meaningful causes
It’s not just about giving—it’s about giving strategically.
If you’re working with clients—or managing your own retirement income—QCDs should be part of the conversation every year. The difference between writing a check and using a QCD can mean thousands of dollars in tax savings over time.
Don’t leave your financial future up to chance. Let’s build a plan that gives you confidence today and peace of mind for tomorrow. Click here to schedule a meeting — I’m here to help you take the next step toward financial freedom.
Colin Symons, CIO Lloyd Financial Group
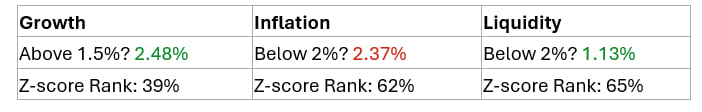
Jobless Claims were 205K vs. exp. 215K. Continuing Claims were up to 1.857MM, from the prev. 1.846MM. No trouble, there.
Philly Fed was 18.1 vs. exp. 4.7, with current activity strong.
New Home sales disappointed at 587K vs. exp. 722K, with mortgage rates and job security cited. Not so hot.
All about oil? Stocks temporarily went down on news the US wouldn’t ban oil exports, then went up on news we would authorize the delivery and sale of oil from Russia. Attacks and news in the Middle East continue, helping markets continue to seek sedation.
On the oil front, Israeli PM Netanyahu said he’s alive (there’ve been rumors,) Iran has no capacity to enrich uranium or make ballistic missiles and the war may be over sooner than people think.
World bond yields continue to rise on stagflation fears, helping supress risk assets. For instance, the 10Y UK gilt hit a yield not seen since 2008, this morning. Stagflation fears seem like the major problem for assets, right now, not oil, per se.
FedEx (FDX) is up 10% after topping expectations and raising their outlook. It’s generally encouraging for the economy when a big transportation company like FDX is doing well.
Super Micro (SMCI) the server maker, is down 22% after three individuals, including a co-founder, were found guilty of smuggling at least $2.5B of US tech into China. If you recall,, the company had major audit issues, which may have been a clue.
OpEx (Options Expiration,) is today to help reset options.
**What does it all mean? **Stagflation fears remains the primary issue as we approach the weekend.
Don’t leave your financial future up to chance. Let’s build a plan that gives you confidence today and peace of mind for tomorrow. Click here to schedule a meeting — I’m here to help you take the next step toward financial freedom.
Disclosures/Regulation:
This content is intended to provide general information about Lloyd Financial. It is not intended to offer or deliver investment advice in any way. Information regarding investment services are provided solely to gain an understanding of our investment philosophy, our strategies and to be able to contact us for further information.
All information has been obtained from sources believed to be reliable, but its accuracy is not guaranteed. There is no representation or warranty as to the current accuracy, reliability or completeness of, nor liability for, decisions based on such information and it should not be relied on as such.
The views expressed in this commentary are subject to change based on market and other conditions. These documents may contain certain statements that may be deemed forward‐looking statements. Please note that any such statements are not guarantees of any future performance and actual results or developments may differ materially from those projected. Any projections, market outlooks, or estimates are based upon certain assumptions and should not be construed as indicative of actual events that will occur.
Past performance is no guarantee of future returns.
Different types of investments involve varying degrees of risk. Therefore, it should not be assumed that future performance of any specific investment or investment strategy will be profitable
Want a clearer view of where you stand? Schedule a free portfolio analysis.
Educational content only. Nothing here is investment, tax or legal advice, and it is not a recommendation to buy or sell anything.