Daily Note
Can Anthropic Kill What’s Already Dead? LFG Daily - November 16, 2026
If you’ve been saving and investing for years, one question eventually comes up: “Am I actually on the right track?”
Many investors have multiple accounts—401(k)s, IRAs, brokerage accounts—but rarely step back to see how everything fits together. That’s why we offer a Free Portfolio Analysis and 1,000-Foot View Financial Plan.
This complimentary review looks at the big picture of your financial life, including:
• Your overall investment allocation • Hidden risks or portfolio overlap • Fees that may be reducing returns • How your investments align with your long-term goals
Think of it as a financial second opinion—a chance to step back and make sure your strategy is built for the future.
If you’d like clarity and confidence about where you stand, schedule your free portfolio analysis today.
Click here to schedule a meeting — I’m here to help you take the next step toward financial freedom.
Dream Bigger, Sleep Better
Colin Symons, CIO Lloyd Financial Group
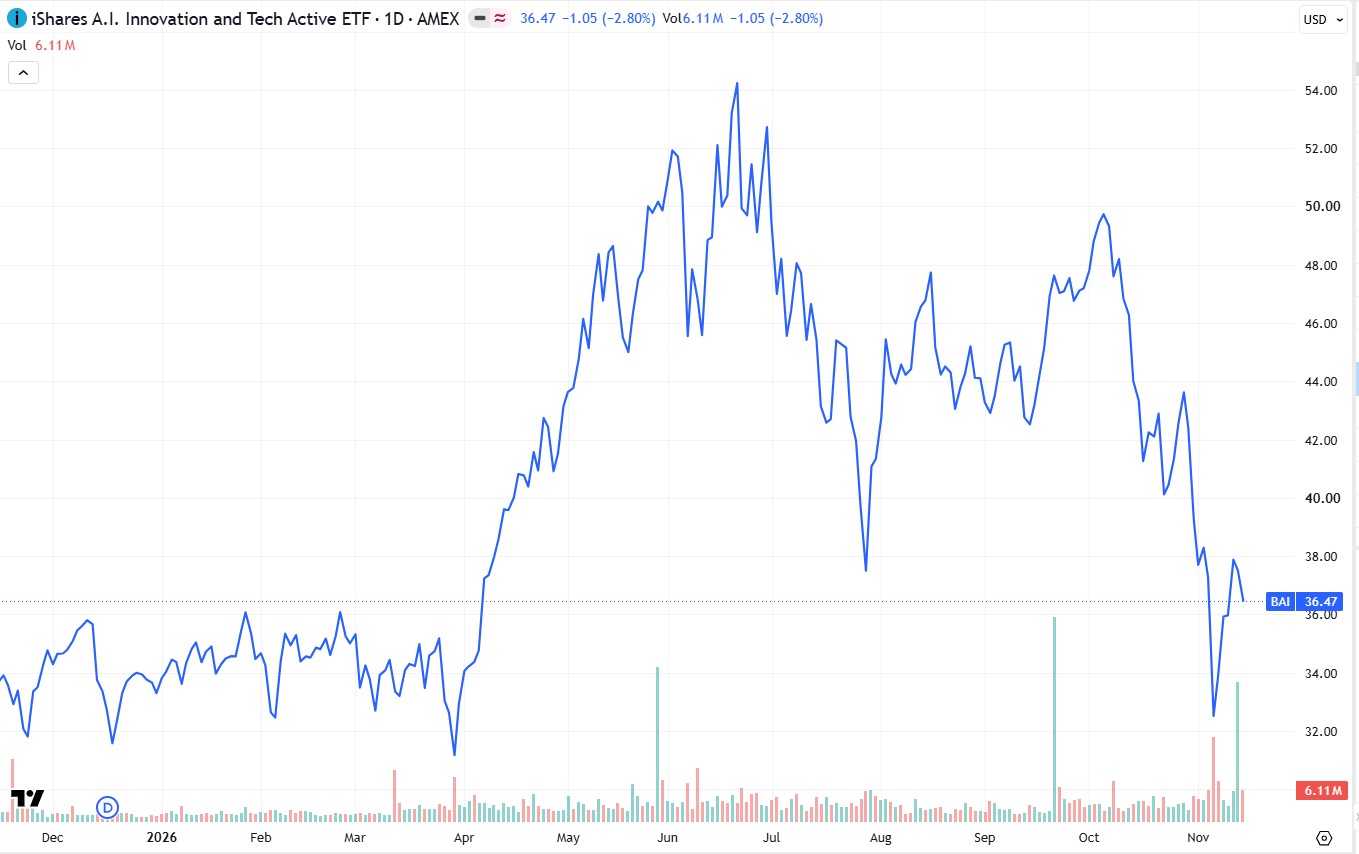
Obviously, there’s a lot of fear in the market, right now. That’s true whether you look at CNN’s Greed & Fear Index, AAII Individual Investor Sentiment, or NAAIM Institutional Investor Exposure. That fear has largely been expressed in the AI space, with the theme continuing to get hit after peaking in July, as can be seen in the chart, below.
One of the reasons cited for the more recent pain is the Anthropic IPO this week. We’ve seen plenty of times where big IPOs have marked the top for a market, and the fear is that we’ll see the same thing happen with Anthropic. I’d call that a chicken-and-egg problem. IPOs cluster around market tops because more IPOs come out when markets are being very friendly. IPOs don’t cause tops, they are caused by tops.
Realistically, Anthropic is looking to extract about $60B from an almost $100T stock market. That’s a rounding error. By itself, that doesn’t matter. It is true that lockup expirations can cause pain for the individual stock, which can potentially have follow-on effects with related companies. In this case, that doesn’t happen until 27 days after the IPO (roughly mid-December,) and it’s hard to say how many will actually use that opportunity.
As of Friday, Bloomberg was reporting six times as much demand for Anthropic shares as there is supply. A benefit of the lower valuation, from $2T to $1.4T, is that leaves more room for strong trading. The valuation isn’t as stretched as it could have been. None of that means Anthropic has to go up and stay up, but maybe this could be something more like the Google (GOOGL) IPO, which many considered overvalued but did great, rather than a sure sign of the end.
For our part, we haven’t bought a new semiconductor position all year until this November wipeout. We bought Sandisk (SNDK) last Tuesday, as the earnings estimate implies a rapid deterioration in earnings, which seems quite unlikely given ongoing memory demand. We also bought surrounding AI businesses, from construction, like Caterpillar (CAT) to suppliers like Credo (CRDO) and TTM Technologies (TTMI.) Admittedly, CAT and TTMI aren’t pure-play AI companies, but they’ve been hit by the fallout and should rebound in a recovery.
I’d add that while we normally try to find opportunities that we think we can own for a year or more, I’m less certain about that, here. AI is a very mature theme and it’s reasonable to believe we could see a slowdown, though we see no current sign of that. There are concerns, and at a certain price, they won’t be discounted. The Huang resignation does take out a big face of the industry, along with concerns there may be more problems, there. For instance, does Nvidia’s willingness to finance AI companies continue at the same pace?
We have also had ongoing issues with inflation and rates, which in my mind is the fundamental problem, rather than anything wrong with AI. To what extent can we fund AI and the government at the same time, and do inflation problems continue to linger? That sparked a hiking cycle, and there’s going to be a race there between how much we hike rates and how much earnings growth slows.
Our basic idea here is that we’ve wiped out enough aggressive longs in early November that we’ve likely set a bottom. Days like Friday sure test that thesis, but looking at the chart above, we’re still well above recent lows. From where we are, the Anthropic IPO is at least as likely to spur greed as it is fear. If, by chance, we see the ETF hit new lows, we’ll likely start trimming our AI stocks. As it is, though, we think there’s enormous potential for strong gains, here. And last week, we put a good portion of our money where our mouth is.
PPI was reasonably encouraging, with the Core 0.3% m/m, as expected, while the Headline was 0.3% m/m vs. exp. 0.4%. That’s the smallest increase since July, but headline is still 6.5% Y/Y, the highest since 2022.
The components that go into PCE inflation were on the softer side, so now that’s unlikely to be an issue. It seems we’ve survived another month of inflation data, and early returns on next month look pretty encouraging. Inflation can easily be an issue over time, but we look like we’ve passed the bad news for a while.
Meanwhile, while PPI was being reported, Fed head Goolsbee was talking about how inflation is broad-based and going the wrong way. Sounds like politics to me, as the actual data says inflation isn’t the problem. There is an energy shock, but real rates have been the issue as there’s so much credit demand.
The AI trade is getting hit again today, maybe on a note from BofA that NAND spot prices have fallen 20% from October as orders from phones and Chinese cloud providers slow. However, the report also says there’s been no reduction from the US, and they expect DRAM and HBM prices to keep rising.
We also had the Constellation Energy (CEG) CEO say grid operators massively overestimated how many data centers are coming online. However, he also said 8.5GW of contracts were signed this year, running to the 2040s and guidance has been raised twice on demand.
NVDA’s ex-CEO is weighing a return to the company following widespread support.
Empire Fed Manufacturing today and Fed head Warsh talks.
**Bottom Line: **Fear in the AI space remains high as we start a big week.
Click here to schedule a meeting — I’m here to help you take the next step toward financial freedom.
Disclosures/Regulation:
This content is intended to provide general information about Lloyd Financial. It is not intended to offer or deliver investment advice in any way. Information regarding investment services are provided solely to gain an understanding of our investment philosophy, our strategies and to be able to contact us for further information.
All information has been obtained from sources believed to be reliable, but its accuracy is not guaranteed. There is no representation or warranty as to the current accuracy, reliability or completeness of, nor liability for, decisions based on such information and it should not be relied on as such.
The views expressed in this commentary are subject to change based on market and other conditions. These documents may contain certain statements that may be deemed forward‐looking statements. Please note that any such statements are not guarantees of any future performance and actual results or developments may differ materially from those projected. Any projections, market outlooks, or estimates are based upon certain assumptions and should not be construed as indicative of actual events that will occur.
Past performance is no guarantee of future returns.
Different types of investments involve varying degrees of risk. Therefore, it should not be assumed that future performance of any specific investment or investment strategy will be profitable
Educational content only. Nothing here is investment, tax or legal advice, and it is not a recommendation to buy or sell anything.